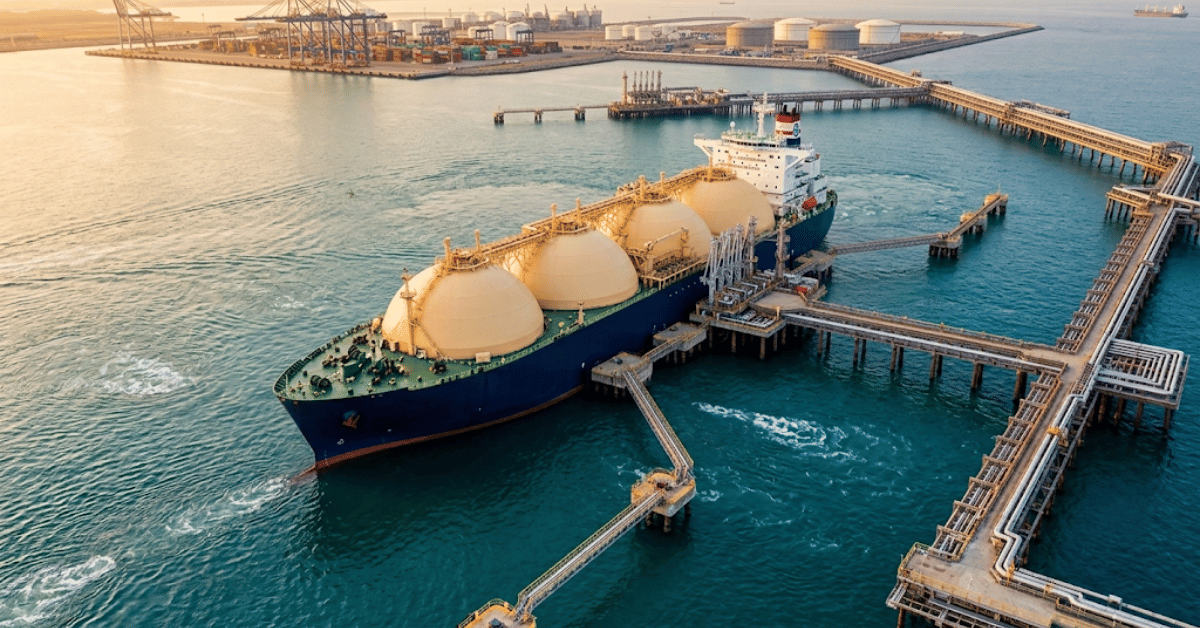
The math on LNG shipping has quietly shifted, and Lloyd's Register's new analysis makes the case that the industry should pay attention. Their finding that a 200,000 cubic meter carrier could boost cargo capacity and cut transport costs, while still fitting most major terminals, is not a radical departure. It is a calibration. The vessel size already exists in the fleet, the terminals already handle the dimensions, and the efficiency gains are measurable. What is striking is not the novelty of the idea, but the discipline of the analysis. This is not about building bigger for the sake of spectacle. It is about matching hull size to real-world infrastructure constraints, and letting the economics follow.
For operators, the practical implication is direct: more cargo per voyage, spread over the same fixed costs, translates into a lower per-tonne transport price. That matters more as the global fleet ages and replacement orders come due. The study is timely, especially when set beside the pressure seen in other corners of the maritime energy trade. Consider the Gulf of Oman STS Transfers Max Out Amid Rising Saudi Oil Exports, where ship-to-ship transfers have hit their ceiling. That is a story about physical bottlenecks in one region. This LNG analysis is about designing around them before they appear. Both point to the same truth: the limits of current infrastructure are becoming a competitive factor, not just a logistical footnote. And while the Atlantic Circulation Weakens: Global Climate Reshaping Predicted reminds us that the broader climate system is sending signals of its own, the shipping industry still has to move energy efficiently in the near term. These are not competing priorities, but they do require different timelines.
Our take is that Lloyd's Register has handed the market a decision point, not a mandate. The analysis shows compatibility with most major terminals, but "most" is not "all." That caveat matters. A fleet renewal strategy built around 200,000 cubic metre vessels will require operators to map their trade routes against terminal constraints, and to accept that some ports will remain out of reach. That is not a flaw in the study; it is the nature of a global system that was never built to a single standard. The smart play is to treat this as a portfolio question, not a universal solution. For a reader deciding on newbuilds or charters, the takeaway is concrete: validate your specific terminal mix, run the cost model on your actual voyage patterns, and let the data decide. The vessel size is viable, but viability is not the same as universality.
The open question is whether the market moves as one, or fragments into operators who adopt the larger standard and those who stay with the older, smaller tonnage for route flexibility. We would tell a reader asking about this to watch the orderbook. If the next wave of LNG newbuilds skews toward 200,000 cubic metres, that is a signal that the industry has accepted the logic. If it stays mixed, then the cost advantage will remain available to those who can use it, but it will not reshape the market overnight. The concrete detail to watch is terminal compatibility data published by individual operators, because that is where the theoretical becomes operational. The study is a strong argument, but the ocean will have the final say.